First-home buyer mortgage brokers Australia-wide

A clearer way to finance your first home

Understand what you can borrow and compare suitable lenders, with no broker fee for standard first-home buyer loans.

Google + RateMyAgent reviews: 600+
5.0

Access to a wide range of lenders including major banks and specialist lenders.

Where do I start?

Help for every stage of your first-home plan

You don’t need all the answers. Start with the question holding you back and we’ll help build the wider plan.

Work out what I can comfortably afford

We look beyond the maximum loan amount to consider repayments, existing commitments, purchase costs and the buffer you want to keep.

Check my deposit and upfront costs

Your deposit is only part of the cash picture. We map transfer duty, legal costs, inspections, lender costs and a sensible post-settlement buffer.

Understand grants and support

We help you identify lending pathways that may fit, while your solicitor, conveyancer and the relevant government agency confirm formal eligibility.

Get a useful pre-approval

We prepare the application around a realistic price range and explain the conditions, expiry date and property checks that still apply.

Compare lender options

We compare policy, features, rates, fees and loan structure so you can see why one option may suit your position better than another.

Prepare for settlement

Once the contract and formal approval are in place, we coordinate the lending steps and keep you updated through to settlement.

Turn these questions into a clear first-home plan.

Talk to a broker

The broker difference

More help. Less running around. No broker fee.

For standard first-home buyer loans, Manson is paid by the lender when your loan settles. You get help comparing options, preparing the application and managing the process without adding another broker fee to your purchase costs.

With Manson

You make the decisions. We help with the legwork.

  • Understand your borrowing power, deposit and upfront costs.
  • Compare suitable lenders across policy, rates, fees and features.
  • Factor relevant first-home support into your lending plan.
  • Prepare the application and manage lender follow-up.
  • Stay supported through approval and settlement.

Doing it independently

You make the decisions and manage each step yourself.

  • Work through calculators, purchase costs and schemes.
  • Research and approach lenders individually.
  • Compare criteria, rates, fees and fine print.
  • Prepare the application and respond to lender requests.
  • Track approval conditions, finance dates and settlement steps.

Manson receives commission from lenders for arranging eligible home loans.

Let’s make your next step clearer

Tell us where you’re up to and we’ll help you understand your borrowing power, deposit and the pathways that may be available.

Talk to a broker

Real people. Real reviews.

What first-home buyers say

Google Reviews: 248
5.0
Rate My Agent:  451
5.0
A first-home buyer’s dream
Ryan and Sean made buying my first home completely stress-free. Their instructions were clear, they were always polite, and I felt supported throughout.
Joshua F
First-home purchase
With us every step
Ryan was with us every step of our first-home journey. No question felt too silly or went unanswered.
Jason & Stephanie
First-home purchase
Above and beyond
Ryan clearly explained the process, advocated on my behalf and helped me achieve the best possible outcome when purchasing my first property.
Levi D
First-home purchase
Calm, clear and supportive
Ryan and Sean were calm, responsive and supportive. Their clear communication made our first-home purchase feel smooth and straightforward.
Monique M
First-home purchase
A lifelong dream realised
They made buying my first home feel simple, clear and manageable. Their professionalism, advice and genuine support helped turn a lifelong dream into reality for me and my boys.
Nikki T
First-home purchase
A smooth and stress-free first purchase
The Manson team made my first property purchase smooth and stress-free. I felt fully supported, clearly guided and confident throughout the process.
Jaimee N
First-home purchase

Ready
to chat?

Tell us where you’re up to. You don’t need exact figures, and there’s no obligation.
Built on referrals, reviews and repeat clients

Google Review: 250+
5.0
RateMyAgent:  450+
5.0
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.

First home support

Support that may reduce the upfront cost

Federal and state support may reduce the deposit or purchase costs needed upfront. We’ll help you understand which pathways may fit, while formal eligibility is confirmed by the lender or relevant authority.

A clear path forward

From first conversation to settlement

We’ll guide the finance process, keep you updated and help you understand what comes next.
01
Understanding you and your goals

We start with a conversation about what you’re trying to do, your current position and what a good outcome looks like.

02
Gathering the right information

We’ll give you a clear checklist of the information and documents needed to assess the options properly.

03
Research and analysis

Once we have everything, we’ll compare suitable lenders, loan structures and policy options for your situation.

04
Presenting your options

We’ll walk you through the research, explain the trade-offs and agree on the best path forward.

05
Preparing the application

We’ll prepare the application for signing and confirm any final documents needed before submission.

06
Submission and lender assessment

Once submitted, we’ll manage lender questions, keep the process moving and update you along the way.

07
Approval

When the loan is approved, we’ll explain any remaining conditions and what happens next.

08
Preparing for settlement

We’ll help coordinate the final documents and work with the relevant parties to get everything ready.

09
Settlement

Settlement is complete and the new loan is in place.

10
Ongoing reviews

We don’t disappear after settlement. We’ll stay in touch to help keep the loan aligned with your needs.

Got questions?

First-home buyer questions, answered clearly

Do first-home buyers need a 20% deposit?

No. A 20% deposit can help you avoid Lenders Mortgage Insurance and may widen your lender choice, but some buyers purchase with less. Eligible first-home buyers may be able to use the Australian Government 5% Deposit Scheme, while other lower-deposit loans may also be available. You still need to allow for purchase costs and a sensible buffer.

What costs should I budget for besides the deposit?

Depending on the property and support available, costs may include transfer duty, conveyancing or legal fees, building and pest inspections, lender or valuation fees, moving costs, settlement adjustments and immediate repairs or furnishings. Keep a buffer rather than using every available dollar at settlement.

Can I use the Australian Government 5% Deposit Scheme?

Potentially. Eligible first-home buyers can apply through a participating lender with a minimum 5% deposit. Property price caps and scheme rules apply, and the lender must still approve the loan under its normal credit criteria. Check the current cap for the property postcode before relying on the scheme.

What stamp duty support is available for first-home buyers?

It depends on where you buy. Each state and territory has different exemptions, concessions, property-value thresholds and residence requirements. We can help you understand how these costs affect your lending position, while your solicitor or conveyancer should confirm your eligibility and lodge the appropriate application.

Can I get a First Home Owner Grant on an established home?

Usually not. First Home Owner Grants generally apply to new or substantially renovated homes, but the amount, property cap, residence requirements and definition of a new home vary by state or territory. Check the current rules where you are buying before relying on the grant.

Can I combine more than one first-home buyer program?

Sometimes. A buyer may be eligible for more than one form of support, but each program has separate rules, timing and property requirements. Lender participation can also matter. Check the combination before making an offer rather than assuming every benefit can be used together.

When should I seek home-loan pre-approval?

Before you begin making serious offers. A useful pre-approval can help set clearer boundaries, but it is conditional, lender-specific and usually time-limited. It does not replace a property valuation, updated documents or final credit approval once you have a contract.

Can I buy my first home with a partner, friend or family member?

Often, yes. The ownership, loan structure, deposit contributions and each applicant’s financial position all need to be assessed. Scheme eligibility may also change depending on who is buying. A broker can help with lending, while a solicitor or conveyancer should advise on ownership agreements and legal protections.

How are mortgage broker fees and lender commissions handled?

Any fee that applies to your situation will be disclosed before you proceed. Mortgage brokers may also receive commission from a lender when a loan settles. The relevant remuneration, credit information and lender relationship will be explained in the documents provided during the process.

Your broker team

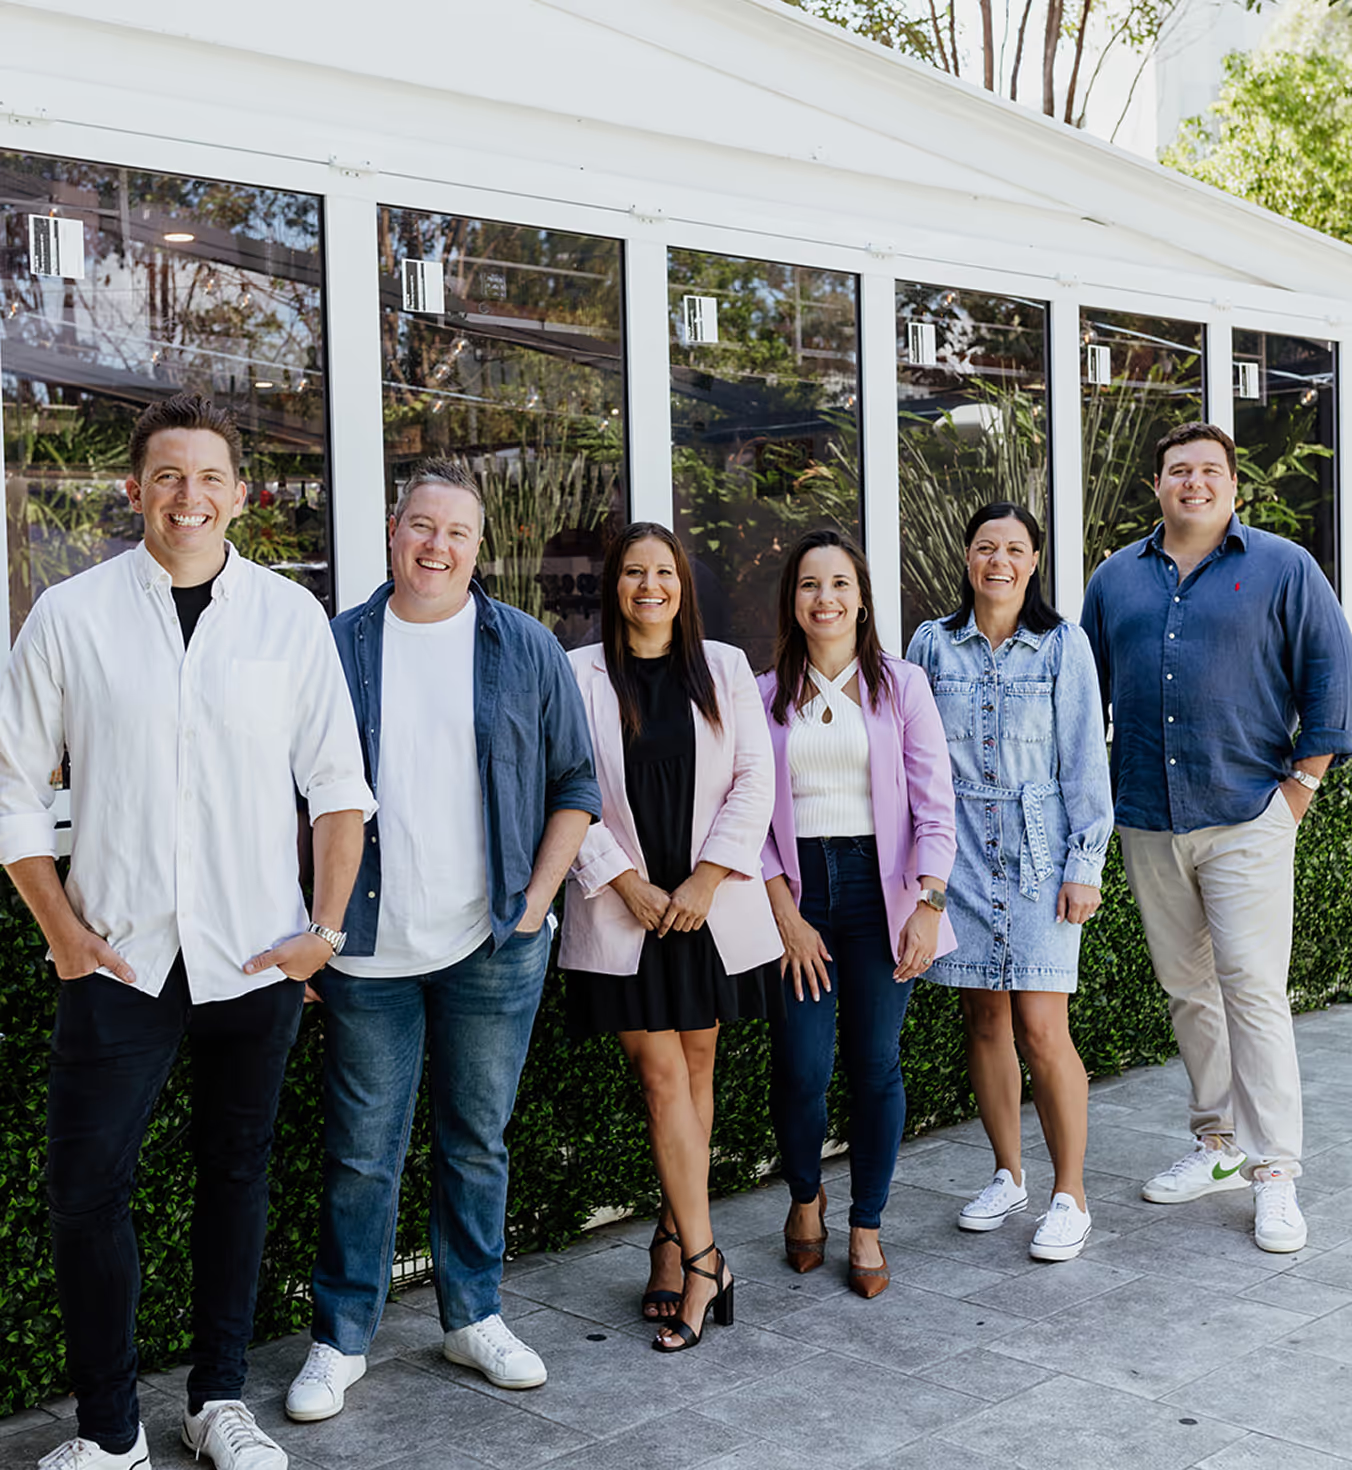
Real people, clear guidance and support that stays with you

The value of a broker is not just finding a lender. It is helping you understand the trade-offs, prepare a stronger application, manage lender questions and know what needs to happen next. Manson supports clients by phone and video across Australia, with in-person appointments available in selected locations.
Partner with Purpose

When you choose Manson Financial Services, you’re helping change lives.